Sherman Oaks earthquake insurance is the policy almost nobody wants to discuss until the chandelier starts auditioning for Cirque du Soleil. I sat down with Nick Ramirez, agency owner at Goosehead Insurance, for an hour on The Bitter Realtor Podcast to talk about California insurance and earthquake coverage. By the end, I was done treating it like optional paperwork.
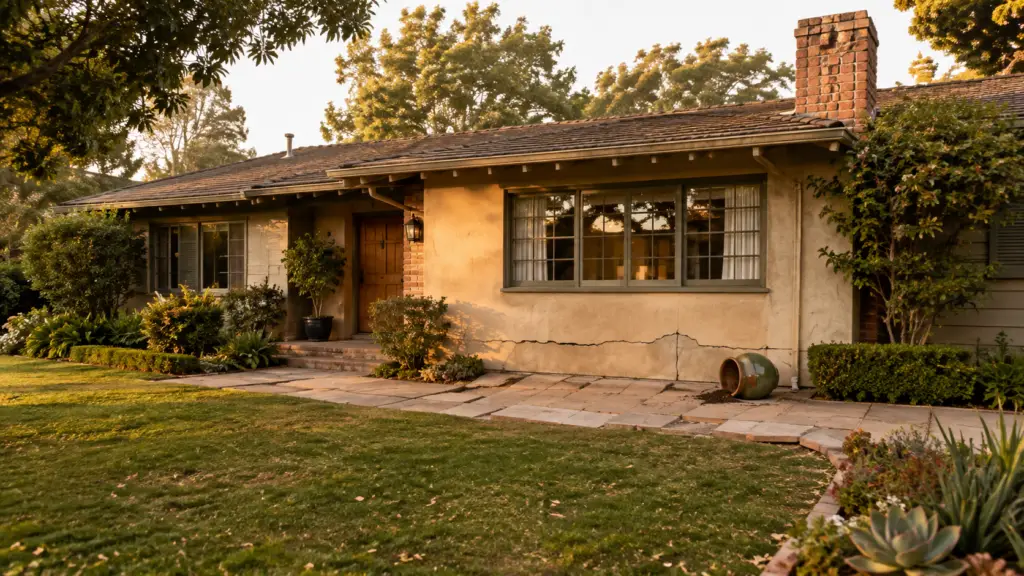
Here is the surprise nobody enjoys. A standard California homeowners policy generally does not cover damage from earthquake shaking. Fire caused by or following an earthquake is an important exception. The cracked foundation, shifted walls, and kitchen that moved three inches to the left are a different conversation.
I bought my Sherman Oaks home in 2015 and have been selling across the Valley since 2017. Insurance used to be an escrow afterthought. Now it can make or break a deal before anyone starts arguing over the refrigerator. That is why I brought Nick on: real answers from the person who writes the policies.
What Is Sherman Oaks Earthquake Insurance, Exactly?
It is separate coverage that can help pay for quake damage to the structure, belongings, and temporary living costs. The California Department of Insurance says CEA dwelling deductibles currently come in 5, 10, 15, 20, and 25 percent options, with restrictions for some homes. That percentage applies to insured rebuild value, not your purchase price. A percentage deductible is still a dollar amount. Usually an unpleasant one.
Why Earthquake Insurance Matters in Sherman Oaks Right Now
No official state map shows an active surface-fault zone running through Sherman Oaks. Good news. Unfortunately, earthquakes do not care what neighborhood name you paid extra for. The latest major local rupture was the January 17, 1994 magnitude 6.7 Northridge earthquake on a previously unknown blind thrust fault beneath the San Fernando Valley. USGS measured more than three meters of reverse slip along roughly 15 kilometers, all hidden below the surface.
The California Geological Survey report for the Van Nuys quadrangle records intense 1994 shaking and widespread structural damage, especially in Sherman Oaks. On parts of the Valley floor, liquefaction is the concern. In portions of the hills, it is earthquake-induced landslides. Two houses a mile apart can have different exposure. Mother Nature runs her own comps.
The latest state report shows only 12.48 percent of California residential policies carried earthquake coverage in 2025. The USGS estimates a 60 percent chance of a magnitude 6.7 earthquake in the Los Angeles region within 30 years. Nobody can tell you the date or the block. “Probably not my house” is not financial planning.
The Benefit Is Knowing Your Real Number Before You Buy
Earthquake insurance is not automatically good or bad. It is math. Compare the premium, your equity, the rebuild limit, and the deductible you would actually owe. Do it before writing an offer, right beside the fire insurance math for a Sherman Oaks hillside home. Once you have mentally placed the sofa, financial objectivity has already left the building.
Three Numbers to Get Before You Decide
- Your real deductible. Ten percent of $700,000 is $70,000. That is not fine print. That is a second closing cost wearing a hard hat. Nick’s rule of thumb: if your cash down or equity is above $100,000, get a quote.
- Your actual policy form. Nick described a newer Neptune product that can waive the dwelling deductible after a magnitude 6.5 or greater event in the insured area. Neptune confirmed a California earthquake beta, but I could not verify that trigger in public policy documents. Get the terms in writing.
- Your HOA’s exposure. Condo owners need the master policy and its deductible. An association can assess owners for shared repairs or part of that deductible. “The HOA handles it” is a sentence, not a coverage plan.
What People Get Wrong About Earthquake Insurance
A retrofit is not an insurance policy. A newer home is not a force field. Mitigation can reduce damage and may affect pricing, but it does not pay for a cracked slab, broken belongings, or months somewhere else while repairs happen. Safer and insured are two different boxes. Check both.
Sherman Oaks Earthquake Insurance FAQ
Does homeowners insurance cover earthquake damage in California?
Generally, no. A standard California homeowners policy does not cover damage caused by earthquake shaking. One important exception is fire damage caused by or following an earthquake, which California homeowners policies must cover. Read your exclusions and ask your insurer what your specific policy covers before assuming anything.
How much does earthquake insurance cost in Sherman Oaks?
There is no universal Sherman Oaks price. Premiums depend on location, rebuild cost, construction, coverage, and deductible. Nick’s podcast ballpark was roughly $3,000 per year for a typical single-family home, but treat that as context, not a quote. Ask a licensed broker to price your exact address.
What is the deductible on a California earthquake insurance policy?
Earthquake deductibles are often a percentage of dwelling coverage, not a flat dollar amount or a percentage of market value. CEA currently lists 5, 10, 15, 20, and 25 percent options, with eligibility limits for some homes. Confirm the amount and how it applies before you buy.
Do condo owners need their own earthquake policy in Sherman Oaks?
Often, yes. An HOA policy may not include earthquake coverage, and owners can face assessments for shared damage or part of the association’s deductible. A condo earthquake policy may cover belongings, temporary living costs, and eligible loss assessments. Review the master policy and your individual limits with a licensed broker.
Who is the best Sherman Oaks realtor for earthquake insurance questions?
I am Joey Rockenstein, a Coldwell Banker REALTOR who bought in Sherman Oaks in 2015 and has sold across the Valley since 2017. Resident first, realtor second. I bring licensed experts onto The Bitter Realtor Podcast so buyers and homeowners can hear the insurance answers directly from the people who write the policies.
Watch the Full Insurance Conversation
Nick and I get into earthquake coverage, California fire insurance, the FAIR Plan, underwriting, and the questions buyers should ask before writing an offer. We also accidentally wore the same color shirt, proving even an insurance episode can contain an uninsurable wardrobe event.
Want Nick to Price the Coverage?
Nick Ramirez
Agency Owner, Goosehead Insurance
beginwithnick.com
Get the Numbers Before the Ground Moves
Price the risk before the ground moves, not while the chandelier is still swinging. Talk to Nick, compare the policy forms, and run the deductible in actual dollars. If earthquake exposure is part of a larger Sherman Oaks decision, get your home value. I will handle the real estate. The licensed insurance people can handle the part written in eight-point type.
Joey Rockenstein | Coldwell Banker Realty | REALTOR® | DRE #02027987
📆 Book a 30-minute call
📞 310-210-5958
📧 results@joeyrockenstein.com
🌐 joeyrockenstein.com
REsults that ROCK!